03
November
2026
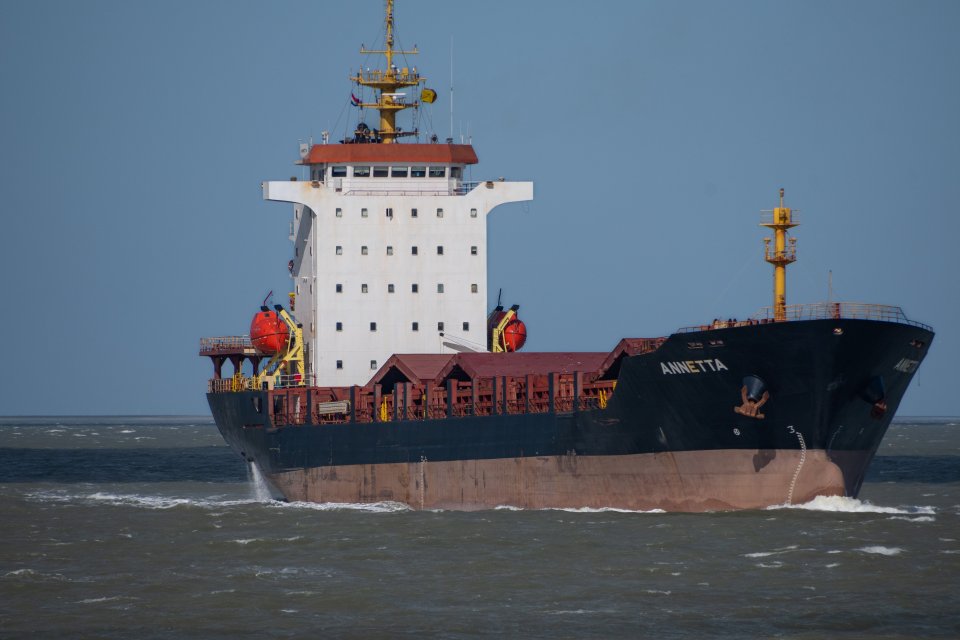
The river-sea coaster market has seen no change over the past few months. Although reports have emerged suggesting that Russia may allow vessels to depart the Sea of Azov, no information has come from the field apart from a few isolated movements. Theoretical freight levels currently stand at USD 24/ton for 3,000 tons of wheat on the Azov–Marmara route, USD 26/ton on the Rostov–Marmara route, and USD 47/ton on the Rostov–Mersin route. If a genuine reopening takes place this week, we will monitor the impact on freight rates.
On routes out of Ukraine, the Black Sea and the Mediterranean, USD 82/ton was paid this week for 6,600 tons of wheat offered on the Reni–Marmara route. Two weeks ago, the same freight rate had been paid for 9,000 tons of wheat transported from Reni to Izmir. A rate of USD 108/ton was paid for 7,700 tons of wheat transported from Reni to Egypt. Last week, 5,000 tons of grain transported from Izmail to Alexandria was being offered at USD 123/ton.
The situation at Romanian ports remains mixed. A rate of USD 55/ton was offered for 4,500 tons of wheat from Braila to the Eastern Mediterranean. Last week, USD 65/ton had been seen on this route. Meanwhile, 6,700 tons of corn from Braila to Marmara was offered at USD 60/ton. However, USD 58/ton was paid for 8,800 tons of corn offered from Braila to Egypt. Freight rates vary depending on the circumstances.
Freight rates on routes out of Novorossiysk were generally trending upward, although they varied depending on the cargo. It was reported that freight for a 5,000-ton coal cargo transported from Novorossiysk to Marmara had exceeded USD 70/ton. A cargo of bran of the same tonnage was being offered at USD 140/ton. Considering that bran has a stowage factor of 80, this can be regarded as equivalent to around USD 80/ton for wheat.
In the larger vessel segments, the Baltic Dry Index (BDI) increased from 2,660 points to 2,712 points. Capesize tonnage moved higher, while Panamax and Supramax moved lower. Handysize tonnage was also broadly flat to slightly weaker.
The Baltic Supramax Index (BSI) pulled back this week from 1,887 points to 1,865 points. Average daily global time charter equivalent (TCE) earnings also declined from USD 23,849/day to USD 23,569/day.
Looking more closely at Supramax routes, daily earnings on the Black Sea–Far East route fell from USD 26,386/day to USD 25,671/day. The decline on the U.S. Gulf–Far East route continued, with average daily earnings falling from USD 30,169/day to USD 29,450/day. Far East averages also declined, easing from USD 22,576/day to USD 22,485/day.
The Baltic Handysize Index (BHSI) weakened by a few points from last week's 1,020 points, falling to 1,014 points. Average daily global time charter equivalent earnings also slipped from USD 18,361/day to USD 18,255/day.
Daily earnings on the Black Sea–Mediterranean and Black Sea–Continent Handysize routes remained at USD 15,500/day for the third consecutive week. The USD 20,000/day level was likewise maintained on the Black Sea–Far East route.
On the South America–Continent route, daily earnings declined this week from USD 30,022/day to USD 29,933/day. Far East averages, meanwhile, recorded a slight increase from USD 18,044/day to USD 18,179/day.
There were some notable sale and purchase transactions this week as well.
Among Ultramax sales, the 66,000 DWT Philippine-built “Delmax66” (2026) was sold for USD 47 million. The vessel is also fitted with an exhaust gas cleaning system (scrubber). The 64,000 DWT Japanese-built “Desert Namuli” (2021) changed hands for USD 38.5 million, while the 63,000 DWT Chinese-built “Libra Confidence” (2019) was sold for USD 33.5 million.
There was a wide variety of Supramax sales. The 58,000 DWT Philippine-built “Charade” (2013) was sold for USD 22.5 million, while the 58,000 DWT Vietnamese-built “Saltwind Explorer” (2011) changed hands for USD 16.5 million. The 58,000 DWT Chinese-built “Kristinita” (2011), also recently having completed her surveys, was sold for USD 20.5 million. Among the older vessels, the 53,000 DWT Chinese-built “Spar Gemini” (2007) changed hands for USD 12.4 million.
Finally, in the Handysize segment, the 38,000 DWT Japanese-built “Union Taylor” (2014) was sold for USD 22 million, while the 38,000 DWT Japanese-built “Fuga” (2012) was sold for USD 19.5 million. In the lower-tonnage segment, the 32,000 DWT Japanese-built sister vessels “Paiwan Wisdom” (2010) and “Daiwan Wisdom” (2010) were sold together as a block deal for USD 23.5 million.
Once again, no coaster sale was reported.
Comments ( 0 )